


- ARA LOGOS Logistics Trust is increasingly diversifying its portfolio with new acquisitions in Australia and lower concentration in its top 10 tenants.
- Its high occupancy rate and manageable debt maturity profile are credit positives too.
- With a little less than two years to call, the ALLTSP 5.5% perp has an attractive indicative ask yield to call of 4.34%.
About ALLT
Previously known as Cache Logistics Trust, ARA LOGOS Logistics Trust (“ALLT”) is in industrial REIT listed on the SGX, having a market capitalisation of S$907m at market’s close yesterday.
ALLT is managed by ARA
Trust Management (Cache) Ltd, a wholly-owned subsidiary of LOGOS, which in turn
is ultimately held by ARA Asset Management Ltd. ARA is a leading APAC real
assets fund manager on a global scale with S$119 billion (as at 31 Dec 20) of
assets under management by the group and its associates. ARA is also ALLT’s largest unitholder controlling
around 10.3% of its shares as at 4Q19. As of end-December, ALLT owns a
portfolio of 27 logistics warehouse properties in Singapore and Australia,
valued at approximately S$1.28 billion.
Major recent acquisition sees heavier focus in Australia assets
Last October, ALLT announced the acquisition of five logistics properties in Australia. The transaction would involve the REIT investing 49.5% in the new LAIVS fund and taking a 40.0% equity stake in Oxford Property Fund. The LAIVS fund holds 4 logistics assets while the Oxford Property fund holds 1 logistic property.
The total acquisition outlay is expected to add to S$441.2m including acquisition fee and other costs. The transaction will be financed through a (1) proposed Ivanhoé and LOGOS Issuance, (2) a private placement of new units to institutional and other investors, (3) a non-renounceable preferential offering of new units to unitholders and (4) external bank borrowings.
The portfolio of the new Australia properties and the fund assets comprise of prime logistics property located in key economic hubs. These include two cold storage facilities, (“the Heron Property”) and a property situated at 1 Hume Road.
Assuming the above acquisition completed, ALLT expects to have a more balanced asset exposure between Singapore and Australia with the total consolidated asset size to increase to S$1.7 billion as at 30 Sep 20.
Table 1: ALLTSP’s property portfolio as at 31 Dec 20
|
No. |
Property |
Valuation |
|
Singapore (valuation in SGD million) |
||
|
1 |
24 Penjuru Road |
261.6 |
|
2 |
2 Fishery Port Road |
124.7 |
|
3 |
51 Alps Avenue |
80.2 |
|
4 |
5 Changi South Lane |
93.6 |
|
5 |
3 Changi South Street 3 |
15.5 |
|
6 |
22 Loyang Lane |
11.2 |
|
7 |
21 Changi North Way |
34.6 |
|
8 |
49 Pandan Road |
37.0 |
|
9 |
15 Gul Way |
27.1 |
|
10 |
1 Greenwich Drive |
149.2 |
|
Sub-total |
834.70 |
|
|
Australia (valuation in AUD million) |
||
|
11 |
127 Orchard Road, Chester Hill, NSW |
55.5 |
|
12 |
16-28 Transport Drive, Somerton, VIC |
32.0 |
|
13 |
51 Musgrave Road, Coopers Plains, QLD |
8.6 |
|
14 |
203 Viking Drive, Wacol, QLD |
28.4 |
|
15 |
223 Viking Drive, Wacol, QLD |
11.6 |
|
16 |
404-450 Findon Road, Kidman Park, Adelaide, SA |
40.0 |
|
17 |
217-225 Boundary Road, Laverton North, VIC |
24.0 |
|
18 |
11-19 Kellar Street, Berrinba, QLD |
12.5 |
|
19 |
3 Sanitarium Drive, Berkeley Vale, NSW |
40.0 |
|
20 |
67-93 National Boulevard, Campbellfield, VIC |
29.5 |
|
21 |
41-51 Mills Road, Braeside, VIC |
36.8 |
|
22 |
41-45 Hydrive Close, Dandenong, VIC |
13.0 |
|
23 |
76-90 Link Drive, Campbellfield, VIC |
13.0 |
|
24 |
196 Viking Drive, Wacol, QLD |
15.5 |
|
25 |
16-24 William Angliss Drive, Laverton North, VIC |
19.0 |
|
26 |
151-155 Woodlands Drive, Braeside, VIC |
17.2 |
|
27 |
182-198 Maidstone Street, Altona, VIC, Australia |
42.5 |
|
Subtotal |
439.05 (S$446.34m) |
|
|
Total portfolio valuation |
S$1,281.04 |
|
|
Source: Company, as at 31 Dec 20 |
||
FY20 results: logistics assets resilient to pandemic
ALLT’s assets are primarily warehouses and distribution centres that mainly operates in the logistics sector. Unlike most other sectors, the pandemic impact on this sector is limited. For the full year FY20 ended December, ALLT recorded gross revenue of S$117.4m, up 3.4% YoY on the back of new leases at ALOG Commodity Hub, AlOG Gul LogisCentre, ALOG Changi Distri Centre 1 and Pandan Logistcis Hub that helped to partially offset the lease expiry at 11-19 Kellar Street, Berrinba.
Meanwhile, property expenses contracted 1% YoY to S$27.4m resulting in a net property income of S$90m for FY20, which was up 4.8% YoY. The increase in net property income was mainly attributable to higher revenue and the lower operating expenses from its Singapore portfolio.
Over FY20, net financing costs fell 7.8% YoY to S$19.8m due to lower interest rates from refinanced loans in Feb 20 as well as lower amount of revolving credit facility drawn. In its business update, ALLT reported an interest coverage ratio of 4.0x for the trailing twelve-month period ended December, up marginally from 3.8x in the corresponding period last year. This is a healthy level in our opinion despite an increased debt load.
Improving portfolio
metrics
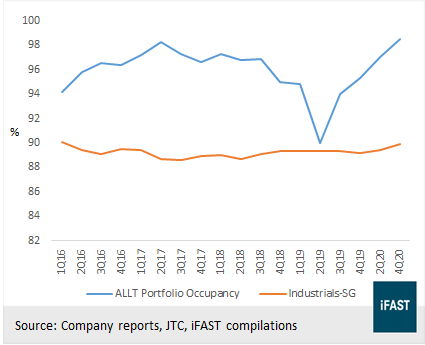
As at 4Q20, ALLTSP’s portfolio occupancy rate stood at 98.5%. The REIT’s assets in both Singapore and Australia achieved decent occupancy rates relative to the industry average, despite a difficult time where most business operations have been paralysed due to the pandemic. ALLT’s Singapore portfolio occupancy rate as at 4Q20 stood at 98.7%, well above the country’s 89.9% occupancy rate for overall industrial property (see Figure 1). Likewise, its Australia portfolio occupancy rate was strong at 98.3%.
Figure 1: Occupancy rates
Near-term lease expiries could exposed to falling rentals although we think this impact is manageable as logistics assets continue to benefit from the uptrend of e-commerce activities. In the coming twelve months for FY21, ALLT will see 27.5% of lease expiries by gross revenue. That said, we believe the trust has taken pro-active steps towards rental expiries, such as commencing early negotiations with existing and potential new tenants. In FY20, ALLT recorded positive rental reversion of 4.8% (2HFY20: 9.8%), a positive sign that logistic assets continued to show strong leasing demand amid the pandemic. Overall, ALLT saw a weighted average lease to expiry of 2.8 years each by NLA and gross rental income, which is still a manageable level.
As at 31 Dec 20, top 10 tenants, which include CWT, DHL, Schenker, and FedEx, make up about 50.8% of its gross rental income. While we note that tenant concentration risk is still on the high side, we also take comfort that ALLT has been putting in effort to reduce tenant concentration risks; contributions from top ten tenants have gradually declined from ~75% in 2016 (4Q18: 63.6%). There is also a greater balance between multi-tenanted and single-user lease structures now. Single-tenant leases fell further to around 29% of ALLT’s gross revenue in 2020 (2018: 33%), compared to 56% in 2016 and 100% at its IPO in 2010.
Credit highlights
While total borrowings rose 1.8% YoY to S$521.9m in 4Q20 (4Q19: S$509.8m), which could be largely due to debt undertaken in relation to the Australia portfolio expansion, aggregate leverage ratio including lease liabilities (debt/total assets) improved to 42.0%, down slightly from 43.3% over the same period. Treating the S$100m ALLTSP 5.5% perpetual securities as debt, we find adjusted leverage ratio at 49.2% as at 31 Dec 20.
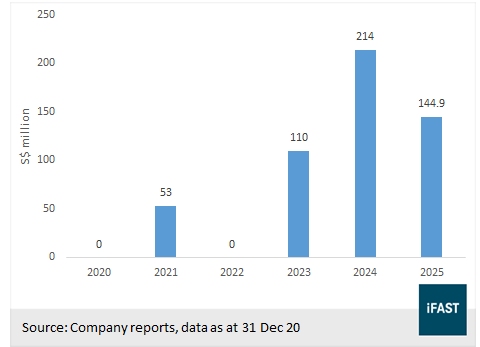
The trust also exhibits a healthy debt maturity profile with the bulk of its debt falling on in 2024 (see Figure 2), a positive sign of proactive capital management. Thanks to a good period of low interest rates, ALLT has partially repaid S$37.0m of term loans using loan drawn downs in Feb 20 and certain loans were partially repaid with equity offerings. Overall, ALLT has a weighted average debt maturity of 3.1 years as at 31 Dec 20 with no major debt commitments until 2023. Hence, ALLT has a low refinancing risk with its gearing level below the regulatory leverage limit of 50%.
Figure 2: ALLT’s debt maturity profile as at 31 Dec 20
The ALLTSP 5.5% perp presents good buying opportunity
To sum things up, ALLT delivered satisfactory results in 2020 and is likely to improve this year in view of a more balanced asset profile between Singapore and Australia. Meanwhile, we also take comfort that the trust has taken good steps towards containing its tenant concentration risk, albeit still having some room to improve.
After weighing the pros and cons, we think the 4.34% yield to call (Z-spread: 398bps) offered by the ALLTSP 5.500% Perpetual Corp (SGD) represents a decent return. The perps are callable at par first on 1 Feb 23, then on every distribution payment date thereafter. If not redeemed at first call, the distribution rate on the notes will reset to the sum of the prevailing SGD 5Y SGD swap offer rate plus the initial spread of 3.58%.
The ALLTSP 5.5% perp provides good value compared to its peers in the industrial REIT sector. Table 2 shows some of the SGD perps in the industrial REIT sector. While the 4.34% yield to call on the ALLTSP 5.5% Perp appears shy of AIMS APAC REIT’s 5.65% Perp (Ask YTC: 4.77%), we nonetheless think that the 4.34% ask YTC on the ALLTSP 5.5% perp is not too shabby for a remaining ~2.0 years to call.
Table 2: Relative comparison
|
Issuer name |
Ticker |
Coupon rate (%) |
First call/reset date |
Ask price |
Ask YTC (%) |
Z-spread to call (Ask; bps) |
|
ESR REIT |
EREIT |
4.60 |
3/11/2022 |
100.21 |
4.47 |
411 |
|
ARA LOGOS Logistics Trust |
ALLTSP |
5.50 |
1/2/2023 |
102.12 |
4.34 |
398 |
|
Mapletree Logistics Trust |
MLTSP |
3.65 |
28/3/2023 |
101.51 |
2.90 |
253 |
|
AIMS APAC REIT |
AAREIT |
5.65 |
14/8/2025 |
103.50 |
4.77 |
408 |
|
Source: Bloomberg Finance L.P., pricing data are indicative only as at 04 Mar 21 |
||||||
Our podcast series, Yield Hunters, is available on Spotify, iTunes Podcasts and Google Podcasts. We share our thoughts on new bond issues and hold discussions on the fixed income space. Listen to our latest episode below and follow us!


